1 Answers sorted by
*
128The log-returns are not linear in the bits. (They aren't even constant for a given level of bits.)
For example, say the market is 1:1, and you have 1 bit of information: you think the odds are 1:2, then Kelly betting you will bet 1/3 of your bankroll and expect to make a ~20% log-return.
Say the market was 1:2, and you had 1 bit of information: you think the odds are 1:4, then Kelly betting, you will bet 1/5 of your bankroll and expect to make a ~27% log-return.
We've already determined that quite different returns can be obtained for the same amount of information.
To get some idea of what's going on, we can plot various scenarios, how much log-returns does the additional bit (or many bits) generate for a fixed market probability. (I've plotted these as two separate charts - one where the market already thinks an event is evens or better,
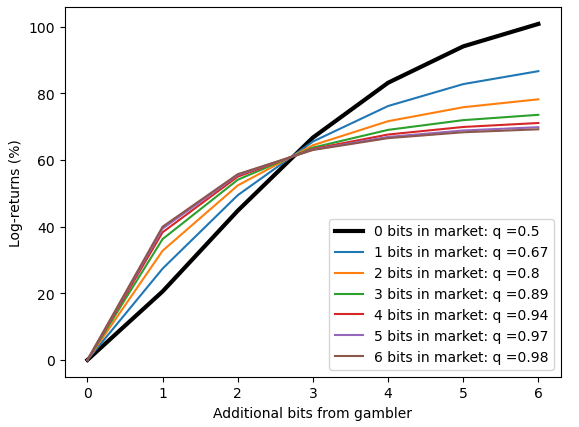
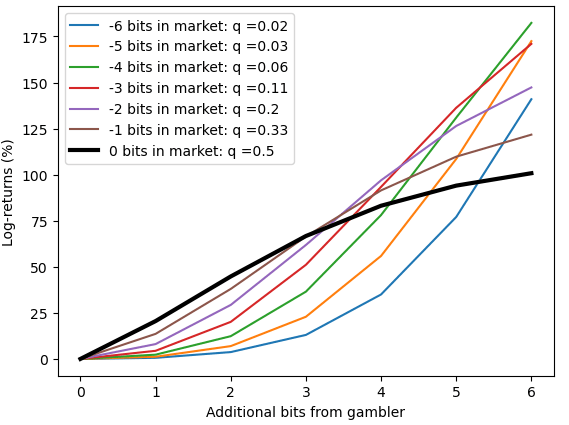
For example, we can spot where the as the market thinks an event is more likely (first chart, 0 bits in the market, 1 bit in the market, etc) and looking at the point where we have 1 bit, we can where we expect to make 20%, then 27% [the examples I worked through first], and more-and-more as the market becomes more confident.
The fact that 1 bit has relatively little value when the market has low probability is also fairly obvious. When there are fairly long odds, 2^(n+1):1 and you think it should be 2^n:1, you will bet approximately(!) 1/2^n, to approximately(!) either double your bankroll or leave it approximately(!) unchanged. So the log-return of these outcomes is capped, but the probability of success keeps declining
There's also a meta-question here which is - why would you expect a strict relationship between bits and return. Ignoring the Kelly framework, we could just look at the expected value of 1 bit of information. The expected value of a market currently priced at q, which should be priced at p is p-q.
When the market has no information (it's 1:1) a single bit is valuable, but when a market has lots of information the marginal bit doesn't move the probabilities as much (and therefore the expected value is smaller)
Recently the whole "if your p(doom) is high, you should short the market" thing has been going around. Let's say the market prices in a 0.1% chance of extinction per century, and you think there's a 50% chance we're dead in the next 25 years. This is about 12 bits of evidence.
Consider: everyone else thinks a company share has a 0.1% chance of being worth $10 tomorrow and a 99.9% chance of being worth $0. I think the chance is 50:50. Therefore the stock price is $0.01 today. If I have $100 in the bank, I maximize expected log(money) by spending fully half of my money on it. By my reckoning the maximum log-expected money is $1581, which corresponds to about a 16-fold increase over $100. Which is not 10 bits of alpha!
PS not looking for investment advice here, just looking for maths.